Mortgage Renewal vs. Refinancing: What Homeowners Need to Know
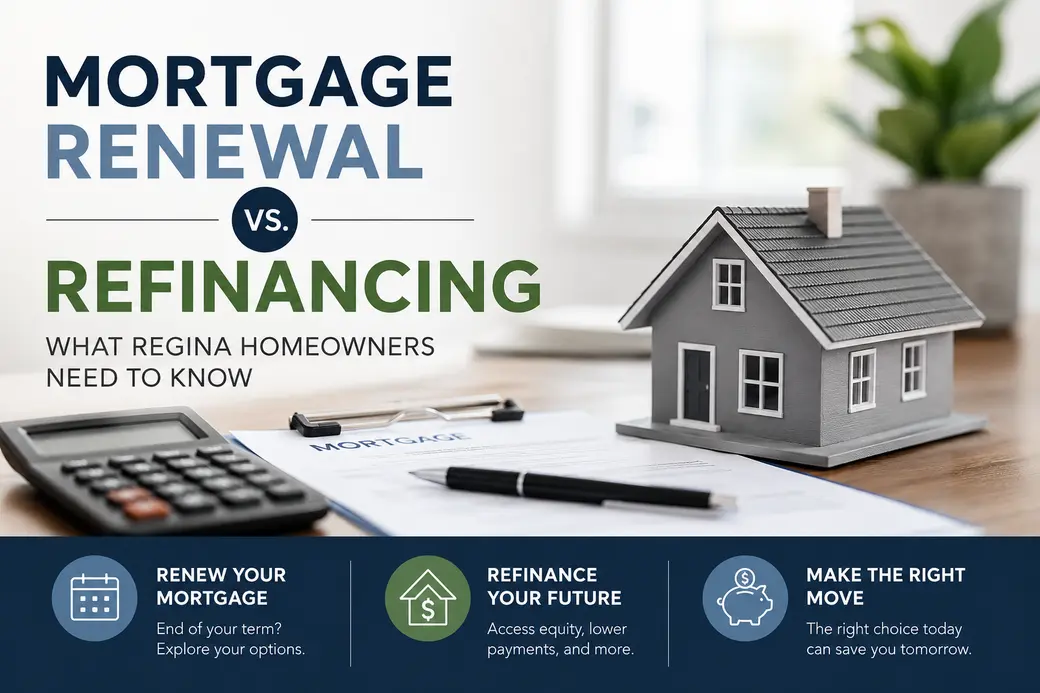
If you’re a homeowner, your mortgage doesn’t just quietly renew itself in the background — at least, it shouldn’t. Mortgage renewal and refinancing are two key moments where the decisions you make can significantly impact your finances, both short- and long-term.
While they’re often mentioned together, renewing and refinancing are very different. Understanding the difference can help you save money, reduce stress, and even unlock opportunities.
Let’s break it down.
What Is a Mortgage Renewal?
A mortgage renewal happens when your current mortgage term ends (typically every 1–5 years). At renewal, you still owe money on your home, and you’ll need to choose new terms to continue paying it off.
This usually includes:
- Selecting a new interest rate
- Choosing a new term length
- Deciding between fixed or variable options
Your lender will typically send a renewal offer — but here’s the catch:
👉 You’re not required to accept it.
Many homeowners simply sign the renewal paperwork for convenience, but this can mean missing out on better rates or more flexible terms elsewhere.
What Is Mortgage Refinancing?
Refinancing allows you to replace your existing mortgage with a new one, often before your term ends, to better suit your current financial goals.
Homeowners commonly refinance to:
- Access equity for renovations, debt consolidation, or major expenses
- Lower monthly payments
- Change amortization length
- Combine multiple debts into one payment
Refinancing can be a powerful tool — but it’s not always the right move. It can involve penalties, fees, and long-term cost considerations that should be reviewed carefully.
Key Differences at a Glance
Mortgage Renewal
- Happens at the end of your term
- No penalty if done at term end
- Keeps your mortgage balance the same
- Ideal time to negotiate rates
Mortgage Refinancing
- Can happen anytime
- May include penalties if done early
- Can increase your mortgage balance
- Useful for accessing equity or restructuring debt
When Should You Start Thinking About Renewal or Refinancing?
Ideally, you should start reviewing your options 3–6 months before your mortgage term ends. This gives you time to:
- Compare lenders
- Lock in competitive rates
- Align your mortgage with upcoming life changes
For refinancing, timing matters even more. Factors like interest rates, home value, remaining balance, and penalties all play a role.
Why Talking to a REALTOR® Matters Too
While lenders and mortgage brokers focus on numbers, a REALTOR® looks at the bigger picture:
- Is it worth refinancing if you plan to sell soon?
- Does your home’s value support accessing equity?
- Would a move make more sense than refinancing?
Having the right advice can help you avoid decisions that look good on paper but don’t align with your long-term plans.
Final Thoughts
Mortgage renewal and refinancing are more than paperwork — they’re opportunities. With the right strategy, you can save thousands, gain flexibility, or set yourself up for your next chapter.Categories
Recent Posts